Factoring vs self-funding your liens: the math nobody walks you through
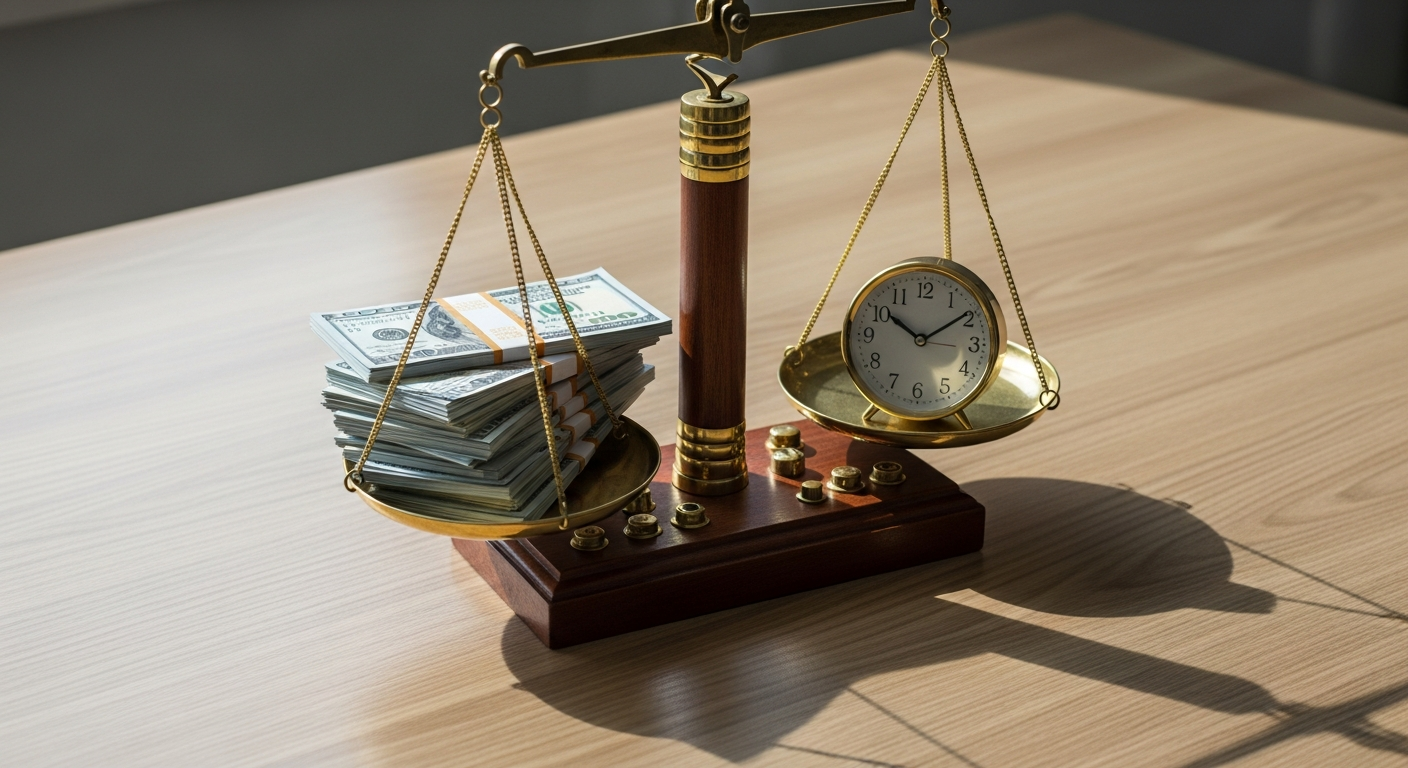
Every PI provider eventually faces the same question: should we factor our liens for immediate cash, or hold them to settlement for the full amount? The honest answer is "it depends" — but most practices don't actually run the math before picking a strategy, and the wrong default can cost six figures a year on a mid-sized book.
The true cost of holding. A nine-month average days-to-payment at a 7% cost of capital is roughly a 5.25% effective discount on the face value of every lien. That's before you account for the staff time spent chasing status updates and producing records, which typically runs another 2-3% of the book in fully loaded labor. So "free money you collect later" is actually closer to a 7-8% reduction on every lien you hold.
The true cost of factoring. Typical factoring rates run 12-18% depending on case profile, attorney quality, balance size, and your historical recovery rate. Bigger books and stronger attorney relationships get the lower end; smaller, less-vetted referrals get the higher end. So the real spread between holding and factoring isn't 18% vs 0 — it's more like 18% vs 8%, which is still meaningful but much narrower than the headline numbers suggest.
The right framework. Most practices should not pick one strategy for all of their liens. Instead, score every case on four dimensions:
1. Attorney win rate and historical reduction behavior. Strong attorneys with low historical reductions are worth holding. 2. Coverage availability and case strength. Cases with clean liability and policy limits well above the medical exposure are lower-risk holds. 3. Your own current cash position. The cost of holding is much higher when you're funding payroll on a line of credit. 4. Case age. Liens that have been sitting for 18+ months without clear movement should be evaluated for factoring rather than continued holding.
Factor the bottom 25-30% of your book by risk score. Hold the top 70-75%. This blended approach typically produces 4-6% more net revenue than either pure strategy, and it dramatically reduces the cash-flow volatility that kills small PI practices.
Questions the case brings up.
Aaron is a CPA and healthcare finance advisor who works with PI medical groups on capital strategy, factoring, and lender relationships.